
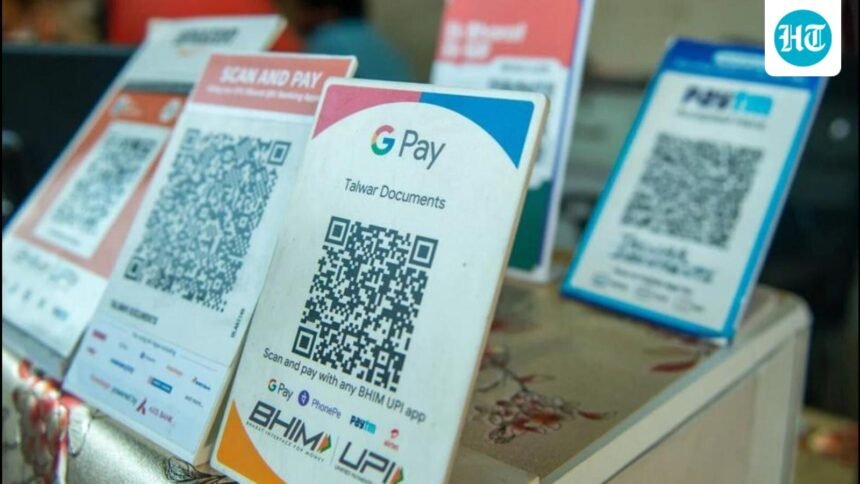
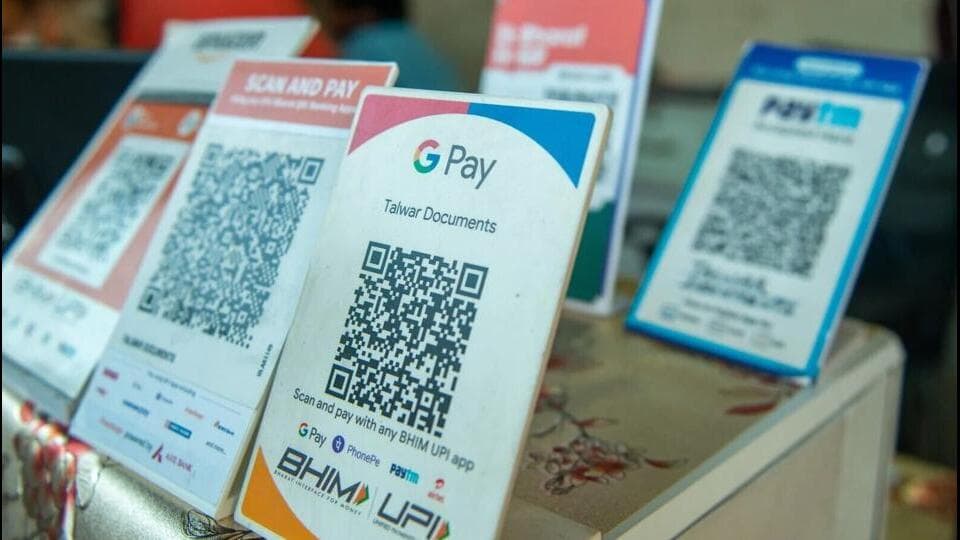
Eighty six percent of UPI, person to merchant (P2M), transactions are below ₹500. Over the last decade, slowly but surely, our expenses have gotten invisible.
No longer is it the large, memorable spending that shrinks our bank account balance. Instead, it is the various, fragmented small spends that add up to a big number by the end of the month. The growth in the volume and value of UPI transactions has long surpassed other digital mediums.
There has been some speculation that the recently announced Merchant Discount Rate of 0.4% on transactions above ₹2,000 could eventually get passed on to the customer and become a deterrent for UPI users for payments to merchants. But as finance ministry data shows, the average UPI transaction has gotten smaller with payments below ₹500 dominating transactions.
Smaller payments, though, do not automatically mean lower expenses for individual spenders.
As an exercise – just visit your UPI transaction history and check your monthly accumulated spend. What’s a bigger surprise, the volume or the value? Top this up with buy – now – pay – later (BNPL) schemes and easy credit card or e-wallet-based digital spending and your monthly expenses get even more fragmented. Now, more than ever before, it has become crucial to have an expense tracking and sorting mechanism in place.
For large purchases, we pause, compare and think twice. However, when the size of a spend is just a few hundred rupees multiple times a day, the mental measurement shifts away from caution. This happens not just because it feels like loose change being spent but also because digital payments are incredibly easy to execute. We no longer count the cash in our wallet before leaving home, so, little to no thought is given to the next small spend that needs a QR scan or a card swipe. Nor do we count the notes and print a balance statement at the ATM while withdrawing cash. It’s a tap of the finger and a four digit pin which guard the money in our bank account. The friction between when you think about the spend to when you execute is reduced to minutes if not seconds.
According to Anand Damani, behavioural scientist and global speaker, “Human behaviour is driven by two variables – motivation and ability to act. The easier it is to act, the lower is the motivation required. When we spend electronically, our account balance is not top of mind and the pain of paying – how much will I have left over – gets reduced. In the absence of ‘pain’, it is now easier for the spending behaviour to occur.”
It’s not just spending that has gone digital. The motivation to spend is increasingly driven by who we follow and what we consume on digital social media.
The constant barrage of information about how others are spending their money or what deals are available across brands or latest fashion, travel destination, luxury trends and so on can easily distract from the need to save for the future.
When this distraction is fulfilled with another invisible spend online, it is easy to miss how much money is stretching beyond affordability. Then, filling this gap — between spending and affordability — with a click on the BNPL tab or paying just the minimum due on the credit card is the spending behaviour that can slowly derail one’s future financial security.
According to Vivek Rege, founder and CEO, VR Wealth Advisors Pvt Ltd, “One must question whether spending is a display of power and status. Jewellery, foreign trips, branded clothes and accessories, these are the kind of expenses that go beyond what we need. People get caught in this power trap and then it’s very difficult to differentiate. Unless you reflect to understand why you are spending, it’s likely to overflow.”
Rege argues that such behaviour is okay for someone with unlimited access to funds but not one whose income is limited, “Don’t make your expenses frictionless if your income is not frictionless. Recently, we find that people who don’t have the money – neither wealth nor sufficient income – are the ones in a hurry to show the world a fake image that everything is okay. You carry the latest iPhone and no one knows whether it is on an EMI. People who have income friction are the ones trying to display frictionless life and that’s where the problem begins.”
What can change this behaviour is self-reflection on why you are spending and whether it is adding value to your life goals.
Audit and Review. Pull out last two to six months of spending across UPI, cards and bank debits. Sort into needs, wants and EMIs. You may not be able to track every small spend every month, but this one time exercise is a good start to get some answers.
For example, is a higher proportion going into random buying from Amazon or too many weekend dinner outings? Check in on your total expenses once a month or once a quarter to reset any spending excesses.
Save before you spend, Damani suggests. When it’s this easy to spend, the only way to manage cashflows is to reverse the cycle of money.
Create your own friction by not allowing yourself to overspend, shift your target monthly savings into an investment or at least a separate bank account at the start of the month itself. This is money you don’t touch, unless in an emergency. Key is to move it out of sight.
Add friction deliberately. If you have too many small, frivolous spends, then lower your daily spend through UPI.
Your bank may not allow any changes on the standard UPI daily transaction limits, but if your behaviour needs the boundary, for a few weeks you can manually monitor and restrict your daily UPI access.
Do not save credit card details on e-commerce websites—entering details creates fresh friction with each buy. Limit spending on wants each month—for example, give yourself two weekend outings a month or two online apparel purchases.
Limit borrowing. If you rely on loans in any format – credit cards, bank loans, BNPL, pay day loans – ensure that you track the aggregate monthly repayment obligation. Rege suggests a maximum EMI to income ratio of 35%-40% including all short and long term loans. Ensure not only to pay the minimum due on your credit card but also pay it in full every billing cycle and check your Credit Report once in a quarter or six months.
Separate the indulgences. You can also create a separate fund for monthly excesses – for unaccounted indulgences or birthday gifts.
This is money you are allowed to spend, just not instantly. “We prefer liquid funds to park this amount, it should come into the picture only if needed. Seen with your bank balance, it signals available surplus rather than monthly excess spending,” says Rege.
Digital, invisible spending is now entrenched in our daily lives and there is no going back. Damani says, “The system can’t reintroduce friction. We ourselves must create friction that’s beneficial. In our financial lives, systematic budgeting is the natural way—customise to make it personal. There is no substitute for discipline.”
Lisa Pallavi Barbora is a freelance writer and author of Money & Her